Search
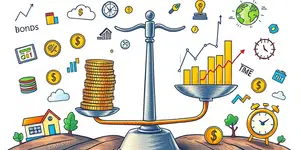
Investing wisely means more than pursuing the highest possible gains. It requires managing the relationship between risk and reward by understanding your goals, timelines, and capacity for loss.
By embracing a measured strategy—one that is a balanced strategy seeks appropriate level of risk—investors can build sustainable growth while safeguarding against unexpected setbacks.
Risk extends beyond a simple decline in share prices. It encompasses many forms of uncertainty, from shifts in interest rates to behavioral missteps under stress. Recognizing these dimensions is the first step toward making informed, confident decisions.
Before selecting stocks or funds, it’s critical to establish a strong financial base. This groundwork not only protects long-term investments but also foster long-term resilience and confidence in your plan.
Your investment timeline determines how much volatility you can tolerate. Shorter horizons demand stability, while longer periods allow you to ride out market swings.
In addition to horizon, consider three dimensions of risk:
Risk tolerance (emotional comfort with losses), risk capacity (financial ability to absorb losses), and risk requirement (the level needed to reach your goal).
Once you’ve set your foundation and clarified timeframes, allocate across asset types to align with your objectives and constraints. Asset allocation is the primary driver of portfolio returns and risk.
Stocks offer the greatest long-term growth potential but come with significant short-term volatility. Bonds tend to deliver income and lower fluctuations but face interest-rate and credit risks. Cash and equivalents provide liquidity and capital preservation but may struggle to outpace inflation.
Alternatives—such as real estate investment trusts, commodities, and private equity—may enhance diversification but introduce illiquidity, complex fees, and valuation challenges. For example, J.P. Morgan’s 2026 forecast projects private equity returns near 10.3%, but these figures are estimates, not guarantees.
When weighing choices, always factor in inflation, taxes, fees, and trading costs. Your expected return is only as meaningful as your real, after-cost outcome.
Diversification spreads risk so no single setback derails your progress. It works at multiple levels:
Mix broad asset classes (stocks, bonds, cash), diversify across geographies (domestic, developed, emerging markets), balance sectors (technology, healthcare, energy), and avoid concentration in individual issuers.
Well-designed diversification seeks to align core objectives with market realities, reducing the impact of any one outcome on your overall plan.
Conclusion: Financial growth is not about avoiding every downturn. It is about taking risks that are understandable, affordable, diversified, and consistent with a long-term plan. By building resilience, matching risk to your horizon, allocating thoughtfully, and diversifying broadly, you can pursue your goals with clarity and confidence.
References